Charitable Donation Appraisals for Personal Property
Charitable donation appraisals document the value of art, antiques, furnishings and collections you plan to give. Prestige Estate Services researches the property and prepares a digital report for you and your tax adviser. We help you plan the work around the gift and filing dates, with clear value findings to support Form 8283 and your tax records.
Work directly with our in-house, IRS-qualified appraisers. Our ISA CAPP appraisal review department checks every formal report before delivery. Routine questions about the findings are included in our support.
Meet Prestige Estate Services
We do not provide real estate appraisals.
An In-House Firm Behind Your Donation Report
All Prestige Estate Services appraisers are in-house W-2 employees. We do not use contract appraisers as members of our appraisal staff. Each appraiser works directly for Prestige Estate Services and is IRS-qualified and USPAP-compliant.
Your assigned appraiser handles the research and report, with support from the Head of Appraisals and office staff. When an object calls for outside specialist knowledge, our firm coordinates that part of the assignment and remains responsible for the work. Meet our appraisers to learn about their backgrounds.
What Do Charitable Donation Appraisals Establish?
The appraisal develops a supported opinion of fair market value for the gift. Under the IRS fair market value definition, this is the price a willing buyer and seller would agree to, with both knowing the facts and neither under pressure. The report explains the market evidence behind that opinion.
Tax donation appraisals give your adviser researched values to use with the gift records. Your tax adviser decides whether the gift qualifies for a deduction and how much you can claim. The appraised value and the allowed deduction can differ.
Why the Original Price May Not Reflect Today’s Value
A purchase receipt shows what you paid at one point in time. By contrast, the appraisal considers the relevant market, the object’s condition and the date the value applies to. The cost to buy a new replacement can also differ from what the donated item would sell for.
For a gift of tangible personal property, the charity’s planned use can affect the deduction. For example, whether a charity will display a painting or sell it may matter. Discuss that plan with the charity and your tax adviser. IRS Publication 526 explains these deduction rules.
Art, Antiques and Other Property You Plan to Give
Charitable donation appraisals can cover a single object, a selected group or a larger collection. We agree on which belongings to include before the work begins. This defines the scope: the property and work covered by the assignment.
Objects That Need Their Own Research
Fine art, antiques, silver, rare books, decorative objects and collections each raise different research questions. An artist’s signature or maker’s mark helps identify an object. Ownership records, age, materials and condition can also affect the value.
Share past appraisals, purchase records, gallery paperwork and records of repairs when available. Those records give the appraiser a starting point. The research still needs to address the actual object and the market relevant to the gift.
Household Belongings and Condition
Used furniture and household goods need useful descriptions too. Federal deduction rules generally require donated clothing and household items to be in good used condition or better. An exception for an individual item with a claimed deduction above $500 requires a qualified appraisal attached to the return. Discuss worn or damaged belongings before the donation so the required evidence is clear.
Do not discard labels, repair records or packaging that may help identify an item. Also tell us about damage or missing parts. These details help us describe what you will actually give.
Appraisals for Form 8283: Reports, Thresholds and Signatures
Non-cash charitable donation appraisals support the property values reported with your tax return. Form 8283 reports noncash gifts; it is separate from the full appraisal report. The filing and appraisal requirements depend on the claimed deduction, property type and applicable exceptions.

When Do the Main Thresholds Apply?
| Claimed deduction | General rule |
|---|---|
| More than $500 in total noncash deductions | You generally file Form 8283. A form requirement alone does not mean every gift needs a qualified appraisal. |
| More than $5,000 for an item or group of similar items | You generally need a qualified appraisal and Section B of Form 8283. Similar items may need to be combined across gifts made during the year, even to different charities. |
| More than $500,000 for an item or group of similar items | You generally must attach the qualified appraisal to the return. Property-specific exceptions still apply. |
Art has an additional rule: a deduction of $20,000 or more generally requires a complete signed appraisal attached to the return. The IRS Instructions for Form 8283 explain these thresholds, exceptions and signature requirements. Your tax preparer applies them to your return.
Who Signs the Form?
For gifts requiring Section B, the appraiser and receiving charity generally complete their assigned parts. The appraiser signs the declaration for the appraisal work. The charity acknowledges receipt of the property; its signature does not establish the appraised value.
Give your preparer the report and the charity’s records together. Check that the object descriptions and gift dates agree across the documents. Form 8283 does not replace the separate written acknowledgment required from the charity when that rule applies.
Plan the Appraisal Before the Donation Deadline
Non-cash charitable donation appraisals need careful timing, especially near year-end. Contact us while the objects and their records remain available. Before booking the work, share the planned gift date and the tax return deadline with us.

The appraiser must generally sign and date the qualified appraisal no earlier than 60 days before the gift. You must receive it before the return’s due date, including extensions, for the year you first claim the deduction. If you first claim the gift on an amended return, obtain the appraisal before filing that return.
The value date also matters. An appraisal report dated on or after the gift must use the donation date for the value. For a report dated before the gift, the value date must fall between 60 days before the gift and the gift date. The inspection date does not set the donation date or the report’s value date. IRS Publication 561 explains these timing rules and the standards for valuing donated property.
What If You Have Already Given the Property?
Tell us when the gift occurred and where the objects are now. We will assess whether access, photographs and records can support the required appraisal. A charity receipt may confirm the gift, but it usually does not contain all the details needed to research value.
Make the Objects and Records Easy to Match
Keep an item list with clear photographs, measurements and any numbers used by the charity. For a multi-part collection, note which pieces belong together. When only part of a collection will be donated, mark that selection clearly.
You need not attend the inspection if access is arranged. Accessible belongings reduce handling time; unpacking and repacking add time when the appraiser must do them. Our appraisers cannot move heavy or oversized objects. If access is limited, we may need more evidence or a better view before including an item.
Charitable Donation Appraisals from Intake to Delivery
We organize the assignment around the gift, the property and your reporting needs. A clear plan at intake helps your appraiser gather the right facts and gives you a useful schedule.
Confirm the Purpose and the Property
Tell us what you plan to give, which charity will receive it and who is preparing your return. We confirm the work, the required dates and the intended users—the people the report is prepared for. You can also request an estimate through intake.
Document the Objects and Research the Market
The appraiser records the relevant physical details and condition, then studies sales and other market evidence. Comparable sales must relate to your actual property. Differences in artist, maker, quality or condition can change how useful a comparison is.
Online asking prices can provide context, but they do not show what a buyer paid. We assess the evidence behind each comparison and explain how it supports the appraised value. As questions arise, your appraiser can discuss the records or details needed.
Agree on a Realistic Schedule
Most formal projects take about two to four weeks after intake, depending on their size, scope and complexity. The on-site intake time also varies. Tell us about a firm deadline at the start so we can assess the work against the time available.
Expedited requests depend on appraiser availability and other projects. Prestige must approve an expedited deadline in writing before it becomes a commitment. Early notice gives us the best chance to plan around a tight timeline.
What You Receive in the Digital Appraisal Report
Charitable donation appraisals should connect each value to the property and evidence behind it. Your digital PDF includes photographs, item descriptions and the research appropriate to the assignment. It states the report’s purpose, the date the values apply to and the people it is prepared for.
The report explains fair market value and the methods used to reach the appraised values. It also addresses relevant assumptions and limits, cites research sources and provides the appraiser’s qualifications. Required signatures and the appraiser’s certification statement form part of the completed report.
Review Within Our Firm Before Delivery
Every formal report goes through our internal quality assurance and quality control process. Our appraisal review department consists of appraisers holding the ISA CAPP designation. They scrutinize the supporting work and report for quality and appropriate reporting under the Uniform Standards of Professional Appraisal Practice (USPAP).
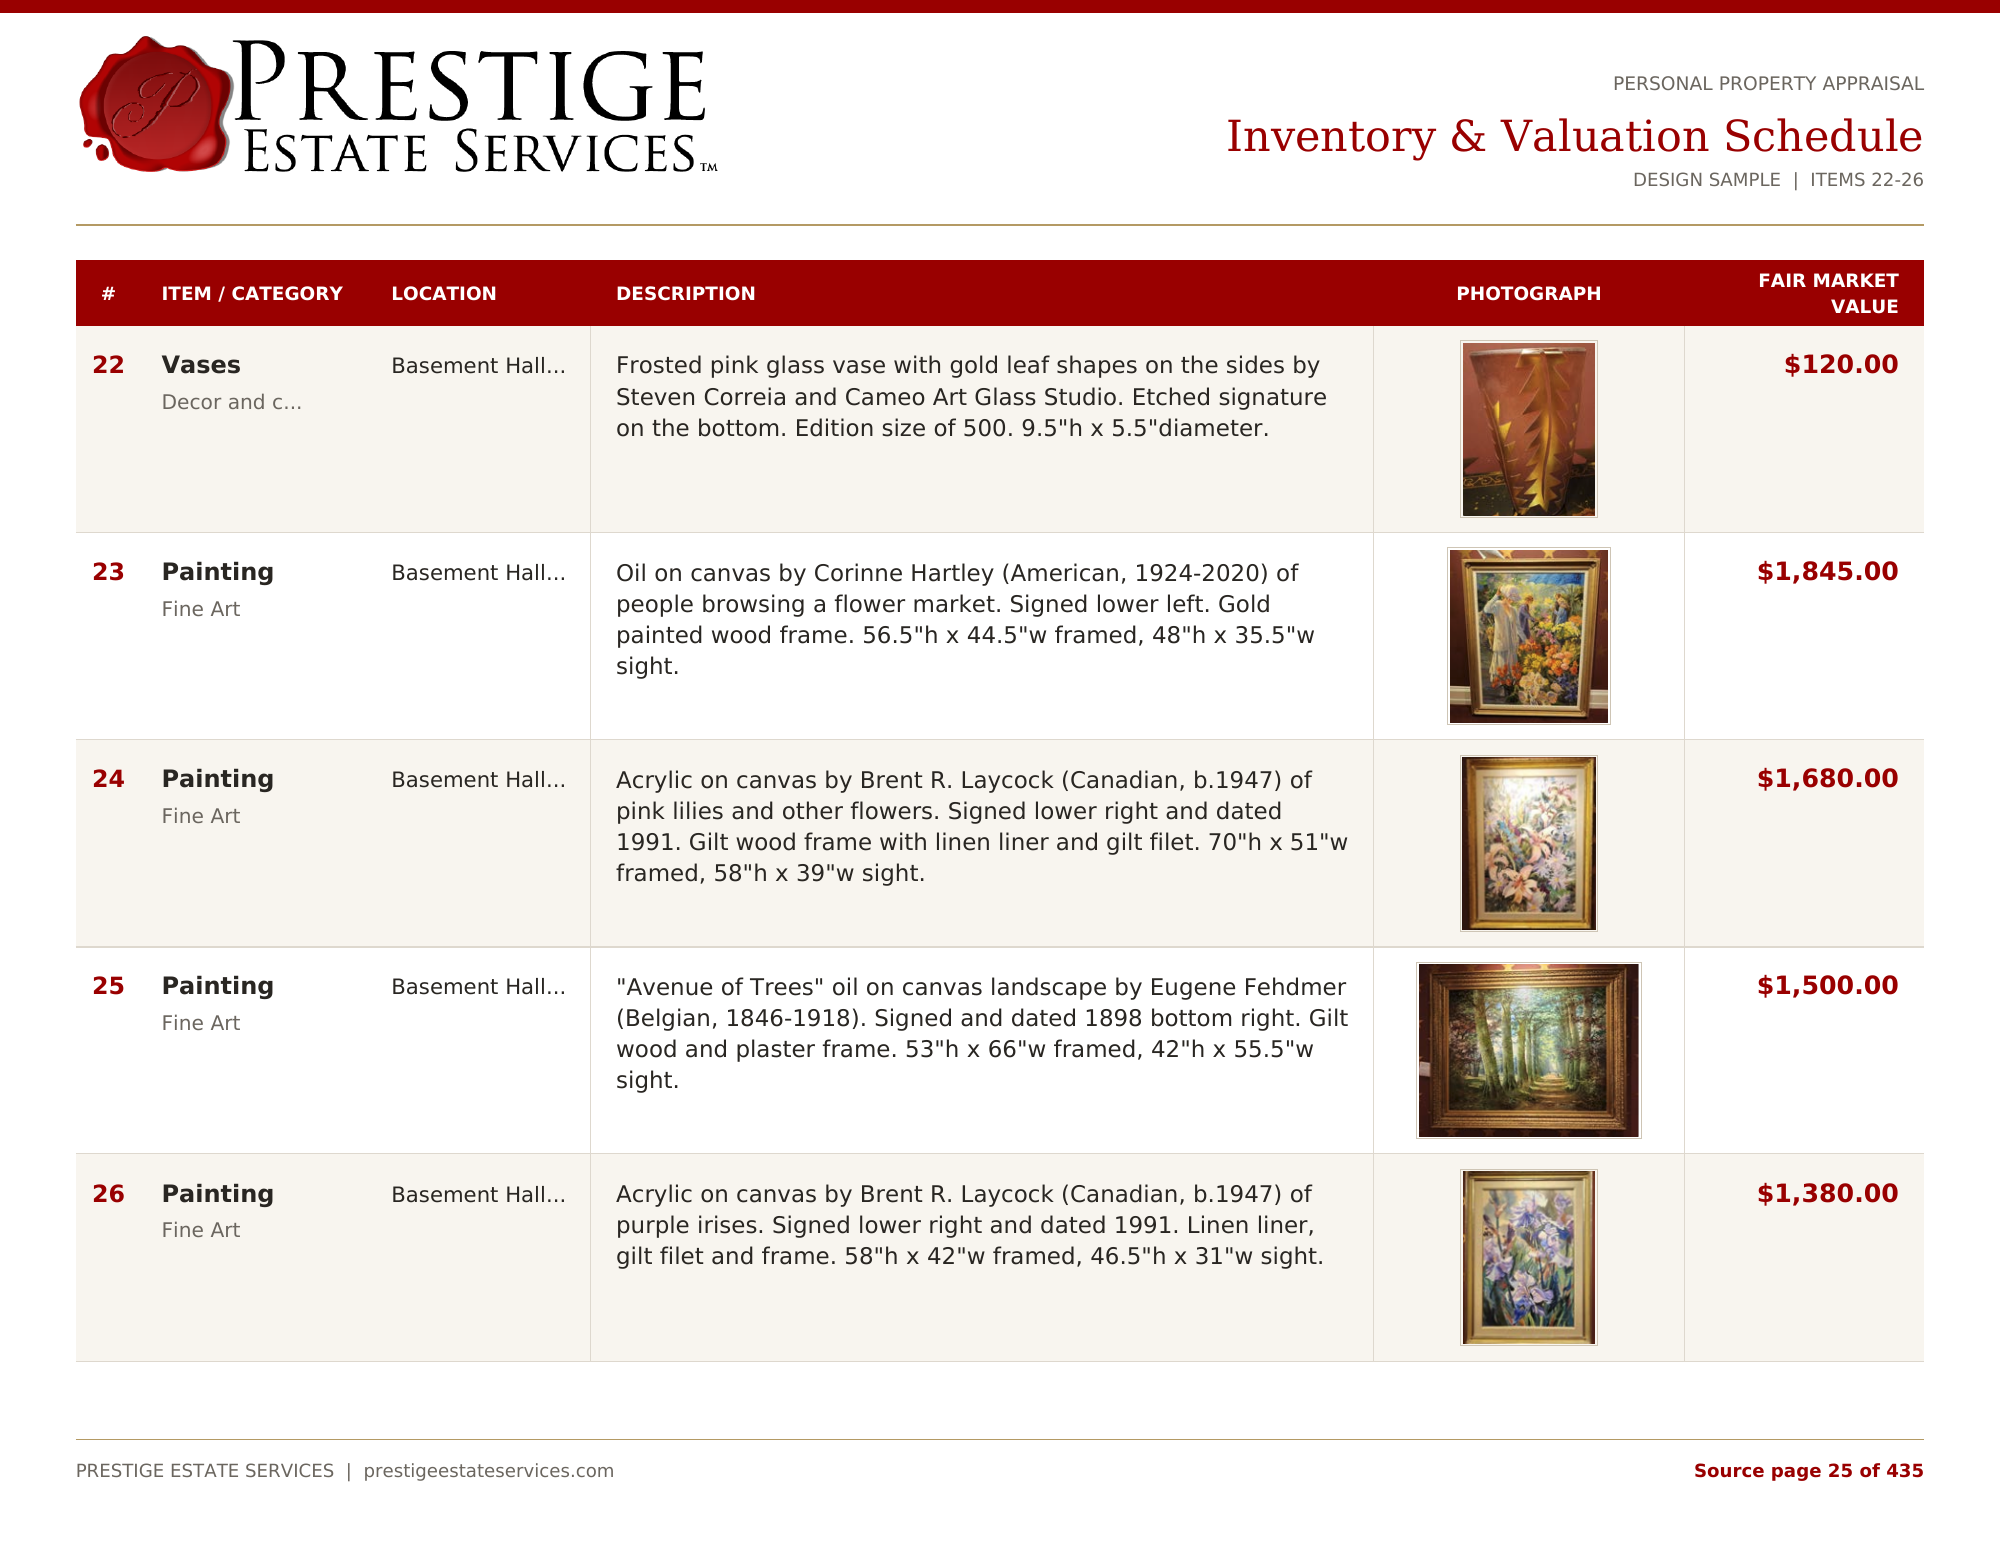
The hypothetical schedule shows one part of a report: photographs and descriptions alongside fair market values. The complete document adds the research, reasoning and other details needed for the agreed appraisal purpose.
Routine questions about the completed report are included in our support. If you later need a report for another purpose, we can discuss the additional work and fees before proceeding. A different use may call for a different value definition or new research.
Clear Estimates for Charitable Donation Appraisals
We estimate the time needed to examine the property, research its value and prepare the agreed report. You can compare that project estimate with our published appraisal fee schedule. This helps you understand the expected work before the project begins.
Good intake information makes the estimate more useful. Send photographs, records, the number and kinds of objects, and their location. For a large household gift, share the property’s square footage and how much fills the rooms or storage space. Research needs can differ greatly between a small art collection and a larger set of everyday furnishings. Fees are not based on the appraised value or deduction.
If the project appears to move beyond the original scope, we pause and discuss the change with you. Written client approval is required before work on the changed scope resumes. New objects or missing records can affect the time needed, so this conversation keeps you involved in the cost decision.
Can Charitable Donation Appraisals Be Completed Remotely?
A formal remote appraisal may suit a donation when photographs and records supply enough evidence. The appraiser needs to assess the object’s identity, dimensions, marks, condition and other relevant facts. A clear front view helps, but images of the back, underside and labels may be just as important.
We assess remote suitability during intake. Some objects need an in-person inspection or further records before we can support the value. Our remote and in-person appraisal guide explains how the two approaches work.
The informal Online Photo Appraisal is a separate service. Its opinion does not replace a formal qualified appraisal when the tax rules require one. You do not need to buy a photo opinion before requesting an estimate for formal work.
Questions About Charitable Donation Appraisals
Does every donation need a qualified appraisal?
No. The requirements depend on the claimed deduction and the kind of property. A qualified appraisal is generally required when a deduction exceeds $5,000 for an item or group of similar items, subject to exceptions. Your tax preparer can confirm which rule applies to your gift.
Can I use the appraisal that was written for my insurance?
An insurance report may contain useful photographs and descriptions. However, its purpose, value basis and date may differ from those needed for the gift. Share it during intake so we can assess what further work is needed for the donation report.
Can one appraisal include property going to several charities?
It may, if the assignment identifies the property, recipients and relevant dates clearly. Separate gifts can also affect how your preparer completes the tax forms. Tell us about all planned recipients when discussing appraisals for Form 8283.
Who chooses the charity and confirms the tax deduction?
You choose the recipient, and your tax adviser addresses the gift’s tax treatment. Before transferring the property, confirm that the charity can accept it and provide the needed records. Prestige’s role is to develop and report the appraised values for the agreed purpose.
What if the charity or gift date changes?
Tell your appraiser and tax adviser before relying on the documents already prepared. A different recipient, date or group of items can affect the report and forms. We will assess what needs to change and discuss any additional work with you.
Do you appraise donated real estate?
No. We do not provide real estate appraisals. Our charitable donation service covers personal belongings such as art, antiques, furnishings and collections.
Searching for “charitable donation appraisers near me”?
Prestige coordinates formal personal property appraisal projects nationwide. Donors comparing firms for tax donation appraisals should consider the property expertise, report process and access needed for the gift.
Match Experience to the Objects
A donor giving paintings needs a different research plan from someone giving a collection of rare books. The appraiser’s knowledge should fit the property, with specialist input arranged when the assignment needs it.
Plan the Inspection Around the Gift
The property location and planned transfer date help determine a practical inspection plan. Depending on the objects and records, the assignment may call for on-site access or a formal remote approach.
Coordinate the Appraisal and Tax Records
A clear property list, recipient details and reporting deadline help the appraiser and tax adviser do their parts. Changes to the gift should reach both professionals while there is time to address the documents.
Tell Us About the Property You Plan to Donate
Share the items, their location, your planned donation date and any filing deadline. Prestige can review the project, explain the next steps and help you obtain an estimate through intake.
Personal Property Appraisal Services Nationwide
Use our locations directory to explore service areas. For a gift involving property in several places, provide each location during intake so we can plan the project as a whole.